Retire to the beach without draining your nest egg.
An interactive planning guide for retirees and soon-to-be retirees. Find out what you qualify for on retirement income, whether to pay cash or finance, and what owning at the coast really costs, all in about ten minutes.
Just want to see if you qualify? Get pre-approved online
What's your retirement home move?
Every retiree's situation is different. Answer four questions and get a personalized game plan with the tools in this guide that matter most for you.
"Can I even get a mortgage without a paycheck?"
Yes. Lenders can't turn you down because of your age, and Social Security, pensions, retirement withdrawals, and even your savings balance can count as income. Enter rough numbers to see an estimated price range.
Estimate only, not a loan approval or commitment to lend. Uses a 49% debt-to-income limit, a 30-year loan at the Mortgage News Daily 30-year fixed average (7.50% on Oct 8, 2026; your rate may differ), 0.31% of the price for property taxes, and 0.25% of the price a year for homeowners insurance (flood insurance, if required, isn't included). Income from savings follows Freddie Mac Guide Section 5307.1 as updated by Bulletin 2026-10: eligible assets minus the down payment and estimated closing costs (about 3.5% of price), divided by 180 months, with a $30,000 minimum. In this guide, income from savings is only counted when the borrower is 59½ or older. Retirement accounts count at 100% only when you can withdraw them without penalty, generally at 59½ (Speak Straight Mortgage), and can't be an account you're already drawing income from. Accounts generally must be seasoned 12 months. Lenders may use the new rule now; it's required for closings on or after Feb 3, 2027. Social Security is counted at face value, with no gross-up. Your actual result depends on the loan program, credit, and documentation.
Keep your nest egg working, or pay off the house on day one?
Paying cash feels safe, but it can tie up a big piece of your savings in a house you can't easily spend. Compare how much savings you'd have under each option over time.
Pay cash
Finance
Illustration only, ignoring taxes, fees, and market swings. Investment returns are not guaranteed, withdrawals from retirement accounts may be taxable, and mortgage interest deductibility depends on your situation. "Net savings" is investments minus any remaining loan balance. Talk with your financial advisor or CPA before deciding.
Budget for more than the mortgage.
At the coast, insurance (including flood), HOA dues, and upkeep can surprise new owners. Delaware also has a realty transfer tax at closing. Adjust these defaults to see a realistic monthly budget and how much cash you'll need to close.
Estimates only. Property taxes vary by address and town, insurance varies by flood zone and construction, and HOA dues vary by community. Get real quotes before you make an offer; Mark works with a Goosehead Insurance partner who can quote homeowners and flood coverage early. Transfer tax structure per Sussex County Recorder of Deeds.
Here's where you stand.
Built from the numbers you entered above. Change anything in Steps 2–4 and this updates instantly.
Talk through my snapshot with MarkGet pre-approved online →Email me my plan
Estimates only, not a loan approval. Based on the assumptions shown in each step.
Six things retirees are told that aren't true.
Tap each myth to see the facts.
MYTH"I'm too old to get a 30-year mortgage."
The Equal Credit Opportunity Act prohibits lenders from discriminating based on age. A 75-year-old can get a 30-year loan if the income and credit work (Experian).
MYTH"Without a paycheck, I won't qualify."
Lenders look at income you can document and assets you can draw from, not whether you still work. Savings, regular withdrawals, and tax-free income can all count (Homes.com).
MYTH"Paying cash is always the smart move."
Sometimes it is. But it can tie up savings you may need for healthcare, travel, or emergencies, and it can mean selling investments at a bad time. Run the comparison in Step 3, and remember you can buy with cash now and take cash back out later if needed.
MYTH"I have to sell my current home before I can buy."
Bridge loans, home equity lines, and asset-based programs can let you buy the beach home first, move once, and then sell up north without a double move or a rushed sale.
MYTH"Reverse mortgages are only for people in trouble."
A HECM for Purchase lets buyers 62 and older buy a new primary home with a larger down payment and no required monthly principal and interest payment while they live there (NRMLA). Taxes, insurance, and upkeep still apply.
MYTH"Delaware taxes my retirement like everywhere else."
Delaware doesn't tax Social Security, and residents 60 and older can exclude up to $12,500 a year of pension and eligible retirement income (Delaware Division of Revenue). There's no sales tax either.
Your move-to-the-coast checklist.
The order matters. Check items off as you go; your progress is included when you request your personalized plan below.
More of your retirement income stays yours.
Low taxes and the coastal lifestyle have made Sussex County one of the fastest-growing retirement destinations on the East Coast.
Delaware does not tax Social Security benefits.
Delaware Division of RevenuePer person, age 60 and older, for pensions and eligible retirement income.
Delaware Dept. of FinanceFrom furniture for the new place to a golf cart, no state sales tax.
IslandsSussex grew about 17% since 2020, roughly five times the national rate.
Financial Advisor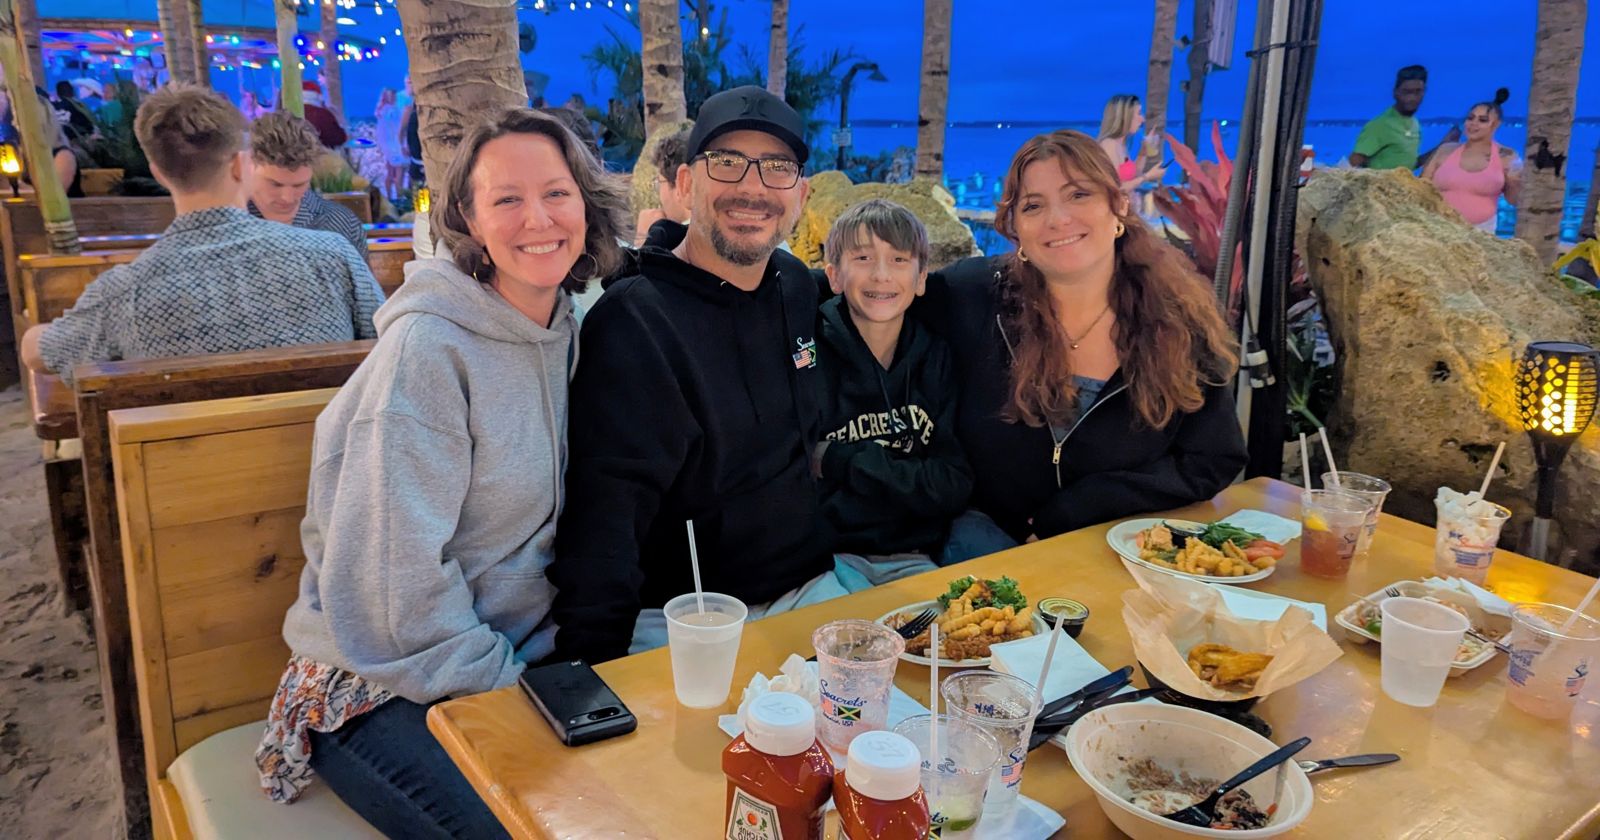
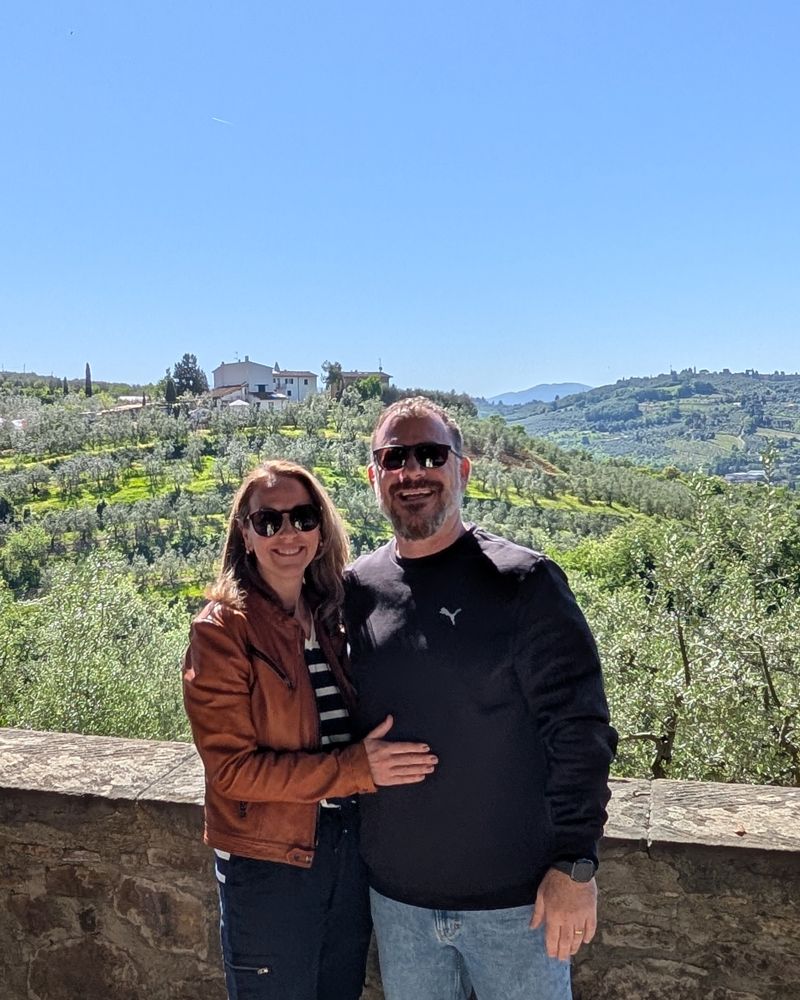
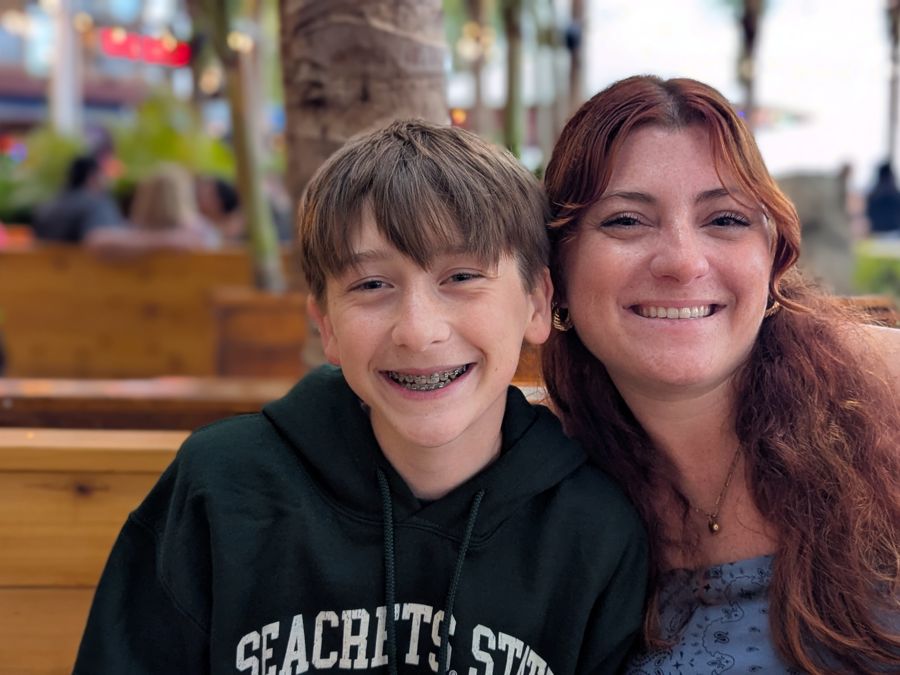
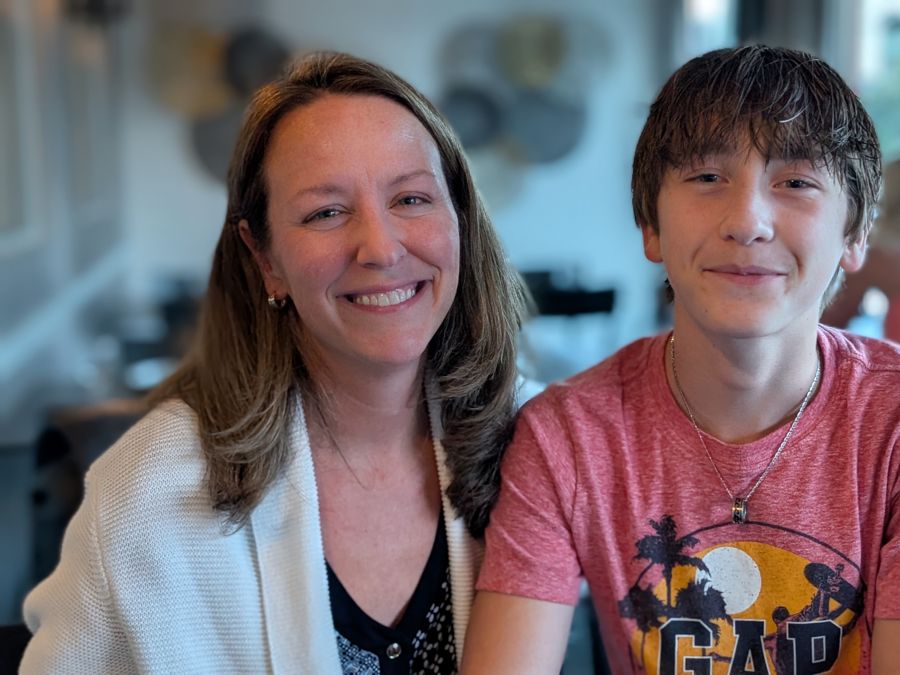
When you work with me, you're treated like family.
Buying a retirement home is personal. You should know exactly who's on the other side of the table.
I've been helping people buy homes across Delmarva for 27 years. The part I love most hasn't changed: sitting down with someone, understanding what they want the next chapter to look like, and finding the loan that gets them there.
Away from the office, you'll find me with my family: dinners at Seacrets, days at the beach, and the occasional trip to see the world. Faith and family keep me grounded, and they're the reason I run my business the way I do.
Many of my clients are retirees making one of the biggest moves of their lives. I treat every one of them the way I'd want my own parents treated: patient explanations, no pressure, and straight answers, even when the honest answer is “let’s wait.”
- Treated like familyPatient, plain-English guidance from first call to closing day.
- No pressure, everYou decide on your timeline. My job is to make the numbers clear.
- Reach me directlyYou'll have my direct number, not a call center.
- Mortgage and insurance know-howI'm also licensed in property and casualty insurance, so coastal insurance costs get planned early.
Pick a time that works for you.
A relaxed, no-obligation conversation by phone or video. Bring your questions, your numbers from this guide, or just your plans.
- What you can qualify for on retirement income
- Cash vs. financing for your situation
- Buying at the beach before selling up north
- Reverse mortgage and home equity options
Prefer to talk now? Call Mark at 302-535-7327.
Choose the conversation that fits
Let's Chat30 minutes · Questions about buying, qualifying, or timing→ Pre-Approval Consult1 hour · Review your income, savings and price range together→ See available times →Opens Mark's secure booking calendar in a new tab.
Get your personalized retirement home plan.
Send me your numbers and I'll put together a no-cost, no-obligation plan: which loan options fit, real rate quotes, and a realistic budget. No pressure and no credit pull to start.
27 years helping Delmarva buyers · NMLS #295348
Book a free callCall 302-535-7327
Licensed in Delaware, Maryland, and Pennsylvania.